
Your Cart is Empty


Design Software History: From Monolithic CAD to Extensible Design Platforms
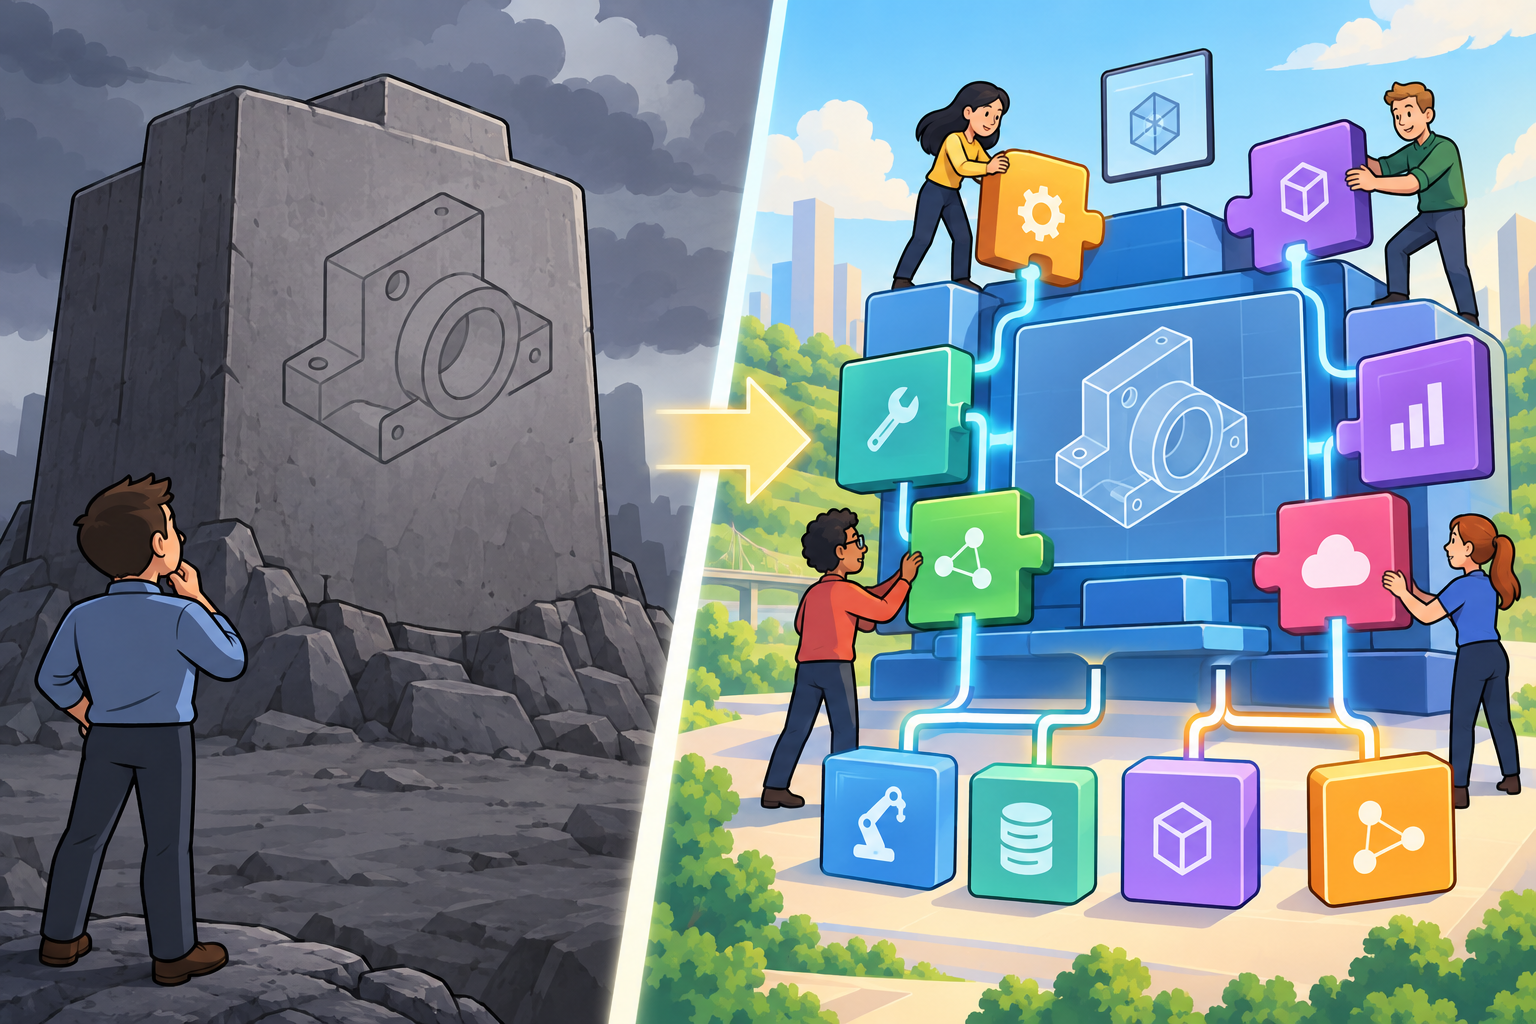


From Monolithic CAD to Extensible Design Platforms
Closed Systems That Still Invited Adaptation
Early computer-aided design systems were usually sold, installed, and understood as closed, self-contained machines rather than open software platforms. In the 1960s, 1970s, and early 1980s, a CAD system often meant a specific combination of proprietary hardware, graphics terminals, digitizers, plotters, operating software, geometry kernels, and vendor-trained operators. Companies such as Computervision, Applicon, Calma, Gerber Scientific, McDonnell Douglas Automation, and Intergraph did not simply sell programs; they sold expensive technical environments that had to be engineered into the manufacturing or engineering department. Yet even these monolithic installations created pressure for adaptation almost immediately, because drafting, plant layout, tooling design, electrical schematics, aerospace lofting, and architectural documentation all had different habits. The gap between a vendor’s general-purpose feature set and a customer’s daily production reality produced one of the earliest truths of CAD history: design software becomes valuable when it can be bent toward local practice. Users wanted repeated commands automated, company drafting standards enforced, title blocks filled, part libraries retrieved, and output formatted for downstream machines. Customization emerged not as a luxury, but as a survival mechanism for making expensive CAD systems pay for themselves in real engineering organizations.
Macros, Scripts, and Lisp as the First Informal Ecosystem
The first extensibility layer in CAD was rarely glamorous. It often consisted of keyboard macros, command scripts, menu customization, batch plotting routines, and small automation utilities written by power users, application engineers, resellers, or consultants. AutoCAD is the decisive historical example because Autodesk, founded by John Walker and colleagues in 1982, placed CAD on relatively affordable microcomputers and then allowed users to reshape it. AutoLISP, introduced in the mid-1980s and based on the Lisp family of programming languages associated with symbolic processing and artificial intelligence research, turned AutoCAD into a programmable drafting environment. Engineers, architects, and independent programmers used AutoLISP to generate geometry, automate annotations, create parametric-like routines before mainstream parametric modeling was common, and enforce company standards. This mattered because customization was no longer confined to the largest aerospace or automotive organizations with dedicated computing departments. A small architectural office, machine shop, civil engineering firm, or reseller could build tools for recurring tasks. In practice, AutoLISP made AutoCAD less a fixed drafting program and more a working language for design production. Long before the phrase “app store” sounded natural, folders of LISP routines, menu files, symbol libraries, and plotting scripts circulated through offices, user groups, bulletin boards, magazines, and reseller networks.
- Macros reduced repetitive drafting operations and standardized common command sequences.
- Command scripts connected CAD work to plotting, batch processing, and documentation routines.
- Lisp automation allowed geometry creation, rule-based drafting, and office-specific productivity tools.
- Vendor APIs gave large customers ways to embed CAD into enterprise engineering workflows.
Enterprise CAD Customization in Workstation Markets
At the high end of the market, customization developed in a different culture. Intergraph, founded by Jim Meadlock and originally tied to mapping, engineering graphics, and plant design systems, served governments, utilities, process industries, and large engineering organizations whose workflows demanded deep integration. Computervision, one of the early leaders in CAD/CAM, sold systems into manufacturing environments where numerically controlled machining, drafting, and product documentation had to be coordinated across departments. The workstation era, especially with Unix systems from vendors such as Sun Microsystems, Silicon Graphics, Hewlett-Packard, and IBM, encouraged a model in which CAD applications could be extended, integrated, and scripted for large-scale engineering production. These customers were not asking only for drawing commands; they wanted database connections, part numbering systems, release procedures, specialized geometry functions, and links to analysis, manufacturing, and procurement. As a result, the informal CAD ecosystem included vendor field engineers, system integrators, in-house automation groups, discipline specialists, and independent consultants who knew both engineering and software. The economic center was different from later downloadable app marketplaces, but the structure was recognizable: a core CAD environment gained value from surrounding expertise, customization code, vertical extensions, and implementation services.
High-End Mechanical Systems and Industry-Specific Extension
Pro/ENGINEER, CATIA, and Unigraphics show how extensibility became inseparable from advanced mechanical design. PTC, founded by Samuel Geisberg and others, released Pro/ENGINEER in the late 1980s and transformed expectations through feature-based, parametric, associative solid modeling. Dassault Systèmes developed CATIA from technology originally connected to Dassault Aviation, and it became deeply influential in aerospace and automotive design through relationships with companies such as Boeing, Airbus, BMW, Mercedes-Benz, and later many global manufacturers. Unigraphics, with roots in United Computing and later McDonnell Douglas before becoming part of what is now Siemens Digital Industries Software, became a central system for complex product engineering, machining, and manufacturing planning. These systems were powerful, but their customers used them in highly specialized ways. Aerospace companies needed tooling, composite structures, wiring, kinematics, configuration control, and certification documentation. Automotive firms needed body-in-white workflows, mold and die design, large assembly management, supplier collaboration, and manufacturing simulations. Vendors could not hard-code every industrial variant, so partner tools, customer-specific extensions, translators, process templates, and automation frameworks grew around the flagship systems. The historical lesson is direct: CAD ecosystems existed before they were branded as ecosystems, because industrial design software was always pulled outward by production complexity.
The Business Shift: CAD Vendors Discover the Platform Model
Third-Party Developers Become Strategic Assets
By the 1990s and early 2000s, CAD vendors increasingly understood that third-party developers did more than fill feature gaps; they amplified the market power of the core product. A CAD system with many specialized extensions could serve more industries without the vendor having to build every niche function internally. Autodesk’s developer efforts, eventually formalized through the Autodesk Developer Network, gave software companies, consultants, and integrators access to documentation, technical support, prerelease information, and marketing channels. SolidWorks, founded in 1993 by Jon Hirschtick and acquired by Dassault Systèmes in 1997, pursued a Windows-native, midrange mechanical CAD strategy in which partner products became essential to the customer proposition. The SolidWorks Partner Program helped create a broad ecosystem around simulation, CAM, product data management, rendering, electrical design, tolerance analysis, cost estimation, and industry-specific automation. This shift marked a business recognition that a CAD vendor’s competitive advantage could come from what others built around it. The platform owner supplied the modeling environment, data structures, user base, and brand credibility, while partners supplied specialization, domain knowledge, rapid innovation, and sales reach into vertical markets that would otherwise be expensive to penetrate.
Partner Networks Around Major Engineering Platforms
Dassault Systèmes, Siemens Digital Industries Software, and PTC each developed platform strategies shaped by the complexity of enterprise engineering. Dassault’s CATIA ecosystem expanded from high-end 3D design into PLM through ENOVIA, simulation through SIMULIA, manufacturing through DELMIA, and eventually the 3DEXPERIENCE platform. In that environment, partners did not merely add menu commands; they connected engineering to manufacturing planning, requirements, systems engineering, visualization, and lifecycle governance. Siemens built ecosystems around NX and Solid Edge, supported by Teamcenter as a major PLM backbone and by manufacturing technologies derived from decades of CAM, machine tool, and production engineering experience. PTC evolved from Pro/ENGINEER into Creo while building Windchill as a major PLM system, and later broadened its story with IoT and augmented reality technologies through ThingWorx and Vuforia. Across these companies, the platform model reflected a shared realization: engineering software is most defensible when it becomes part of an enterprise operating system for product development. Partner networks, implementation specialists, and certified add-ons helped these vendors sell not just modeling commands, but larger transformations in how companies managed parts, assemblies, revisions, simulations, suppliers, and production data.
- Developer programs reduced friction by publishing APIs, sample code, and compatibility guidance.
- Certification programs gave customers confidence that extensions would work with supported releases.
- Partner marketing helped specialized vendors reach the installed base of major CAD platforms.
- Integrator networks translated generic software capability into company-specific implementation results.
Economic Logic of Add-Ons and Vertical Tools
The economics of CAD ecosystems were powerful because specialization in design work is almost endless. A sheet metal designer cares about bend allowances, flat patterns, corner relief, tooling constraints, and press brake production. A mold designer cares about parting surfaces, shrinkage, cooling channels, ejector pins, inserts, and machining strategy. A civil engineer cares about alignments, grading, surfaces, corridors, parcels, and regulatory drawings. A product visualization specialist cares about materials, lighting, camera behavior, animation, and photorealistic rendering. No single CAD vendor could efficiently build every best-in-class tool for every discipline while also maintaining the core modeler, user interface, file formats, graphics pipeline, translators, and release schedule. Add-on vendors turned this impossibility into a market. CAM developers such as Mastercam, GibbsCAM, Delcam, and later many integrated CAM suppliers built manufacturing bridges. Visualization companies such as Luxion with KeyShot, Chaos with V-Ray, and earlier rendering specialists added presentation power. Simulation firms and solver providers connected CAD geometry to finite element analysis, computational fluid dynamics, and motion studies. The platform vendor benefited because each specialized extension made the base CAD license more useful, while the add-on developer benefited from access to an existing user community and data environment.
Resellers and Integrators as the Human Middleware
Resellers and systems integrators became essential because CAD adoption was never only a software installation. They trained users, migrated legacy drawings, wrote macros, configured templates, installed plotters, managed license servers, translated file libraries, built company standards, and sometimes created the custom tools that later became commercial products. In the AutoCAD world, local resellers often knew the needs of architects, surveyors, mechanical contractors, cabinet makers, and municipal engineering offices better than Autodesk could from headquarters. In the SolidWorks ecosystem, value-added resellers built businesses around implementation, training, PDM rollout, simulation adoption, and add-on recommendation. In enterprise PLM deployments around CATIA, NX, Creo, Teamcenter, ENOVIA, and Windchill, integrators translated executive ambitions into workflows for engineering release, supplier collaboration, change management, and compliance. This human layer is easy to overlook when discussing APIs, but historically it was crucial. CAD ecosystems were social and commercial networks before they were digital storefronts. The value moved through seminars, certification classes, user conferences, reseller newsletters, application engineers, industry consultants, and customer advisory boards as much as through software downloads. Platform strategy succeeded only when people and organizations made the technology fit real design practice.
APIs, Marketplaces, and the Cloud Era
From Automation Hooks to Development Frameworks
The technical meaning of a CAD API changed substantially over time. Early customization interfaces often exposed commands as text sequences or allowed limited automation of drawing operations. As CAD systems incorporated object-oriented data models, feature histories, assembly structures, constraints, metadata, and parametric relationships, APIs became more sophisticated. Developers needed access not just to draw a line, but to traverse an assembly tree, interrogate a feature, create a sketch constraint, attach custom properties, export a neutral file, update a drawing view, launch a simulation, or synchronize a part number with a product data system. Windows-based CAD accelerated this shift through technologies such as COM, OLE Automation, Visual Basic for Applications, and later .NET. AutoCAD’s ObjectARX gave C++ developers deep access to its database and graphics system, while its COM automation and later .NET APIs broadened the developer base. SolidWorks exposed a rich API through COM that became central to partner tools and customer automation. In this phase, the API became a contract between the platform owner and the external innovation community. Good documentation, stable behavior, version compatibility, and technical support became strategic concerns because many customers depended on custom code to keep design production moving.
Python, Open Tools, and Computational Design Communities
Python became one of the most important scripting languages in modern design software because it combined readability, broad library support, and strong adoption across scientific computing, automation, and visualization. Rhino, created by Robert McNeel & Associates, became a major platform for computational design through RhinoScript, Python scripting, and especially Grasshopper, originally developed by David Rutten. Grasshopper’s visual programming environment changed architectural and product design culture by making parametric and algorithmic modeling accessible to designers who were not traditional software engineers. FreeCAD, as an open-source parametric modeler, uses Python extensively for scripting and workbench development, creating a different ecosystem model based on community contribution and extensible modules. Blender, although historically associated with animation and visual effects, has become increasingly relevant to product visualization, geometry processing, scripting, and procedural workflows through its Python API. Python also appears in modern engineering pipelines where CAD geometry connects to optimization, data analysis, machine learning, automated meshing, and cloud computation. This matters historically because CAD extensibility moved from vendor-controlled customization toward broader computational design culture. Designers increasingly expected geometry to be generated, analyzed, transformed, and connected to external data rather than manually modeled feature by feature.
- Object-oriented APIs exposed parts, assemblies, drawings, features, constraints, and metadata as programmable objects.
- COM and .NET helped Windows CAD products support automation, add-ins, and enterprise integration.
- Python expanded design automation into architecture, visualization, simulation preparation, and research workflows.
- Visual programming made algorithmic design accessible to non-specialist programmers.
Marketplaces and Downloadable CAD Extensions
Once software distribution moved online, CAD ecosystems became more visible. The Autodesk App Store organized extensions for AutoCAD, Revit, Inventor, Civil 3D, Fusion, and other Autodesk products into a marketplace-style environment where users could discover add-ons for productivity, documentation, manufacturing, architecture, analysis, and data exchange. The Onshape App Store represented a different model because Onshape, founded by former SolidWorks leaders including Jon Hirschtick, John McEleney, and others, was cloud-native from the beginning. Instead of treating the CAD file as a local object passed between desktop applications, Onshape made design data accessible through browser-based collaboration, versioning, and APIs. Fusion 360 extensions further reflected the subscription and services era by packaging advanced manufacturing, simulation, nesting, generative design, and data management capabilities as modular entitlements connected to Autodesk’s cloud strategy. Rhino and Grasshopper plugin communities, including tools such as Kangaroo for physics-based form finding, Ladybug and Honeybee for environmental analysis, and many fabrication-oriented components, showed how a flexible host application could become a laboratory for design methods. These marketplaces and communities made the ecosystem legible: users could see that the CAD product was no longer the whole solution, but the center of a wider tool constellation.
Cloud-Native CAD and Design Data as a Platform
Cloud-native CAD changed the ecosystem model because it weakened the traditional assumption that design work revolved around isolated files on local machines. In file-based workflows, external applications often needed imports, exports, translators, plug-ins, and careful version control to avoid data loss or duplication. In cloud-based systems, applications can connect directly to design data through web APIs, permissions, and shared services. This makes it easier for simulation, rendering, manufacturing quoting, procurement checks, collaboration dashboards, and documentation tools to operate as external services rather than locally installed add-ins. REST APIs, webhooks, OAuth-based authentication, cloud storage, and browser-accessible geometry viewers changed expectations about where CAD data lives and how it is used. Autodesk Platform Services, formerly known as Forge, exemplifies this direction by offering APIs for model viewing, data management, design automation, and construction workflows. Onshape’s architecture also illustrates the shift, because part studios, assemblies, drawings, release management, and collaboration are inherently connected to a database-like cloud backend. Historically, this is a major transition: CAD became less like a standalone drafting or modeling application and more like a design data platform. The ecosystem moved from plugin menus inside desktop software toward distributed services that interact with persistent engineering data.
Why CAD App Ecosystems Changed Design Software History
Innovation Moved to the Edges of the Platform
The rise of CAD app ecosystems changed design software history by moving much of the innovation to the edges of the platform. Core CAD vendors still mattered enormously because they controlled modeling kernels, geometry editing, user experience, file formats, APIs, licensing, and market access. However, small developers, consultants, research groups, and specialized software companies could often solve focused problems faster than large vendors. A niche developer building a mold cooling analysis tool, a Grasshopper environmental analysis component, a Revit documentation automation add-in, a SolidWorks costing utility, or an NX manufacturing connector could concentrate on one workflow with unusual depth. The platform vendor, by contrast, had to balance thousands of customer requests, backward compatibility, internationalization, quality assurance, kernel changes, graphics performance, and commercial priorities. This division of labor made ecosystems productive. The best CAD platforms became innovation amplifiers: they provided enough stability and reach for external developers to take risks, while customers benefited from solutions that would never have appeared quickly inside the main product roadmap. This pattern also explains why developer relations, documentation quality, sample projects, version compatibility, and marketplace visibility became historically important components of design software strategy.
Competition Became a Battle of Surrounding Networks
CAD competition used to be described primarily in terms of modeling features: wireframe versus surface modeling, 2D drafting versus 3D solids, direct modeling versus parametric history, or local desktop performance versus cloud collaboration. Those distinctions still matter, but ecosystems changed the basis of competition. A CAD system became more attractive when it had strong CAM integrations, trusted rendering pipelines, reliable simulation connections, mature PDM or PLM links, active user communities, and a large pool of trained consultants. File access and API depth became strategic advantages because they determined how easily customers could connect the system to existing workflows. Conversely, weak APIs, unstable extension points, restrictive licensing, poor documentation, or closed data structures could limit adoption even when modeling features were impressive. This created new tensions. Platform owners wanted to control quality, security, monetization, and customer relationships. Developers wanted stable access, fair certification processes, predictable commercial rules, and protection from being displaced by native features. Customers wanted openness, interoperability, and long-term control over their design data. The ecosystem therefore introduced a political economy into CAD: platform control, interoperability, licensing, and data ownership became as consequential as sketch constraints or surface continuity.
- A strong ecosystem increases confidence that a CAD system can support specialized workflows.
- Open, stable APIs help customers protect investments in automation and integration.
- Marketplace control can improve quality, but it can also create dependency on platform governance.
- Cloud data platforms make collaboration easier, while raising sharper questions about ownership and portability.
The Central Historical Argument
The history of CAD app ecosystems shows that modern design software is not defined only by modeling commands, geometry kernels, or user interface design. It is defined by the networks that form around the software: independent developers, resellers, consultants, vertical specialists, cloud service providers, plugin authors, academic researchers, open-source contributors, and enterprise integrators. AutoLISP routines passed between AutoCAD users, Intergraph and Computervision customization in large engineering organizations, CATIA and Unigraphics extensions for aerospace and automotive production, SolidWorks partner tools, Rhino and Grasshopper communities, Autodesk marketplace apps, Onshape cloud integrations, and Fusion 360 extensions all belong to the same long arc. Each stage reflects the same underlying reality: design work is too varied, too technical, and too economically specific to be fully contained inside a single vendor’s application. The most important CAD systems in history became platforms because users needed them to become platforms. They accumulated languages, APIs, partners, connectors, services, and communities until the boundary between the core product and the surrounding ecosystem became strategically inseparable. The rise of CAD app ecosystems proves that design software history is also the history of extensibility, specialization, and shared innovation, not merely the history of better modeling features.
Also in Design News






